


Why Countries Are Quietly Diversifying Away from the Dollar
In 1957, Muddy Waters recorded what would become one of the defining songs in the history of the blues: I've Got My Mojo Working. Although the song was originally written by Preston "Red" Foster and first recorded by Ann Cole, it was Muddy Waters' electrifying version that transformed it into a classic. His unforgettable performance at the 1960 Newport Jazz Festival cemented its place in music history and helped inspire generations of rock musicians.
Sources: YouTube & Wikipedia
If you are unfamiliar with this blues standard, I encourage you to listen to the YouTube version of the song below from this iconic live performance before continuing.
Muddy Waters Band, Got My Mojo Working---Live at Newport Jazz Festival, July 3 1960
The song revolves around one simple but memorable lyric:
"I've got my mojo working, but it just don't work on you."
In blues tradition, a "mojo" referred to far more than confidence. It was a magical charm believed to bring luck, influence, attraction, or personal power. The irony of the song is that despite possessing all the charisma and confidence in the world, the singer cannot persuade the one person he most wants to win over.
Oddly enough, that lyric provides an interesting way to think about today's U.S. dollar.
As we discussed in Part One of this series, the dollar's influence remains remarkably strong. It continues to serve as the world's primary reserve currency, plays a central role in international trade and finance, and remains the destination investors flock to whenever global uncertainty rises. Reports of its impending demise have been greatly exaggerated.
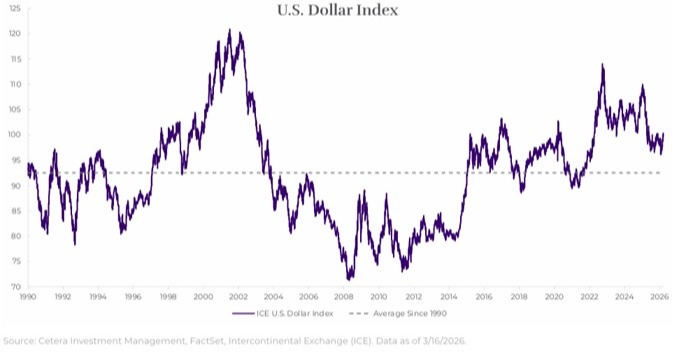
The first thing you'll notice is that the U.S. dollar has continued to trade above its long-term average since 1990, despite a steady stream of articles, social media posts, and media hand-wringing predicting its decline.
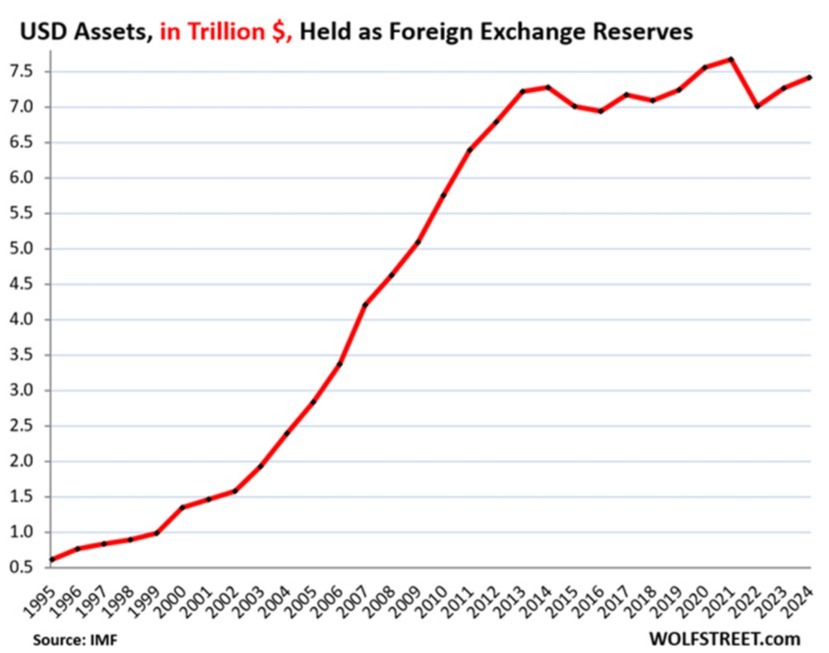
The second thing you'll notice is that the total value of foreign exchange reserves held in U.S. dollars has remained remarkably stable over the past fifteen years. Since 2010, foreign countries around the world have typically held between $7.0 and $7.5 trillion in U.S. dollar-denominated assets. This simply doesn't support the popular narrative that governments and central banks around the world are abandoning the greenback.
At the same time, something important has changed over the past several years. While the dollar still wields tremendous influence, many countries have quietly begun seeking ways to reduce their dependence on it. Not because another currency is poised to take its place, but because relying so heavily on any one country's financial system creates risks of its own.
That distinction matters.
This story is not about China replacing the United States or the euro overtaking the dollar. It is not really about replacement at all. It is about diversification.
One event more than any other accelerated that conversation.
Following Russia's invasion of Ukraine in 2022, the United States and its allies froze hundreds of billions of dollars of Russian central bank reserves. Whether readers agree or disagree with that decision politically is beside the point. The broader financial lesson was impossible for governments around the world to ignore.
For decades, many countries had viewed reserve assets held in the Western financial system as largely untouchable. Suddenly, they realized those same assets could become powerful tools of geopolitical policy. Central bankers everywhere began asking themselves a reasonable question: If Russia's reserves could be frozen, what might happen if our country someday found itself on the wrong side of Washington and its allies?
That question changed incentives.
Interestingly, what happened next was far more subtle than many headlines suggested. Countries did not rush to sell dollars and replace them with Chinese yuan. Instead, they behaved much like disciplined investors who realize they may have become overly concentrated in a single asset. Rather than making an all-or-nothing decision, they gradually broadened their holdings.
They diversified.
As shown in our next chart below, rather than making dramatic shifts, many central banks gradually increased their holdings of Canadian dollars, Australian dollars, Swiss francs, Singapore dollars, South Korean won, and several other currencies. The dollar's share of global reserves declined modestly, not because one rival suddenly emerged, but because several smaller currencies each captured a slightly larger slice of the pie.
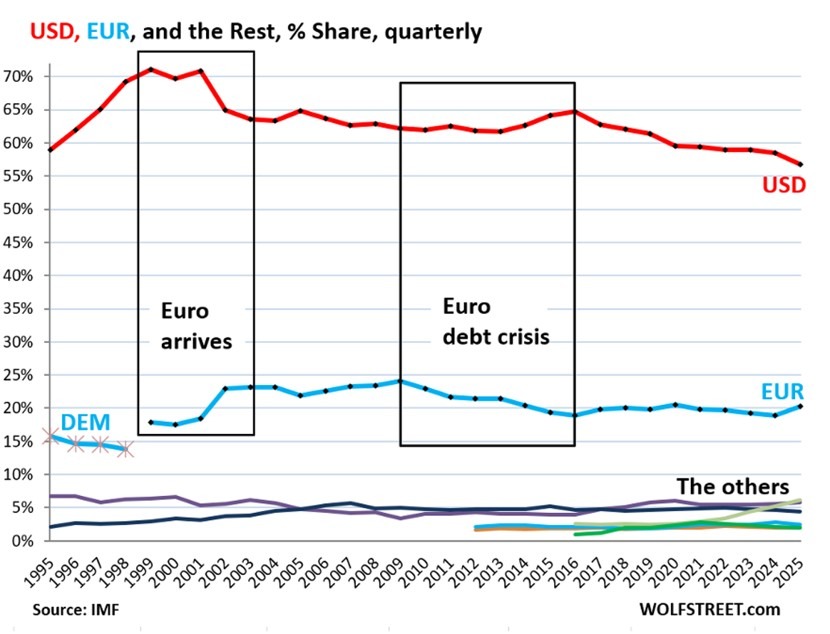
That is a very different story than "the dollar is being replaced."
In fact, it is remarkably similar to the advice that savvy financial advisors give our clients. Diversification is not a vote of no confidence in your largest holding. It is simply recognition that concentrating too much risk in any one investment can create unnecessary vulnerability. The same principle applies to central banks managing hundreds of billions of dollars in reserve assets.
Gold tells a similar story. Gold isn't replacing the dollar. It's complementing it.
Over the past several years, central banks have purchased gold at one of the fastest rates in modern history. As you will note in our final chart below from Frank Holmes of U.S. Global Investors, after briefly selling some of their gold reserves when prices were near all-time records this spring, central banks resumed their gold purchases as prices fell in response to the war in the Middle East.
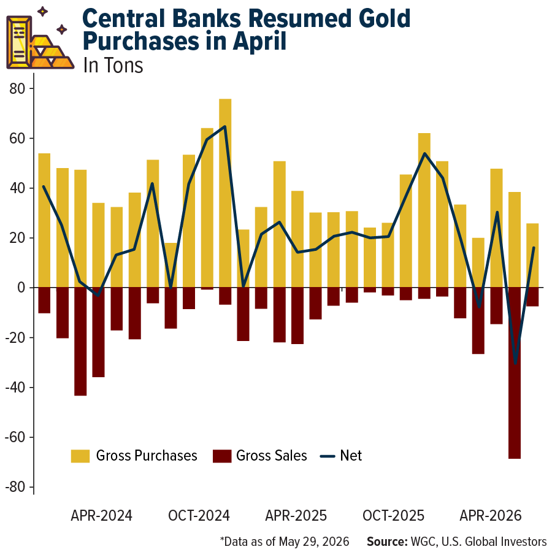
Some commentators have interpreted this elevated level of gold buying as evidence that the world is abandoning the dollar. I believe the evidence points to a more nuanced conclusion.
Unlike foreign currencies held in another country's banking system, gold cannot be electronically frozen. It does not depend on the SWIFT payment network, nor is it the liability of another government. In a world where geopolitical tensions have intensified, those characteristics provide an additional layer of financial insurance. Once again, the motivation appears to be diversification rather than replacement.
Perhaps the most important lesson is that reserve currency status isn't an election.
It's an ecosystem.
Countries do not wake up one morning and vote to replace the world's reserve currency. Instead, millions of financial decisions by governments, corporations, banks, investors, and central banks gradually reshape the monetary landscape over many years - and often many decades.
This is why so much of the public conversation about "de-dollarization" can be misleading. That may be the single biggest misunderstanding in today's conversation about the dollar.
Decline and replacement are not the same thing. A currency can gradually lose market share while remaining the indispensable foundation of the global financial system because no alternative currently offers the same combination of liquidity, legal protections, market depth, transparency, and worldwide acceptance.
History suggests that trust takes generations to build and, more often than not, years to lose.
The euro remains constrained by the absence of a unified fiscal and political system. China's economy is enormous, but capital controls, legal uncertainties, and limited financial transparency continue to discourage broader adoption of the yuan. Gold serves an important purpose but cannot efficiently support the day-to-day needs of modern global commerce.
In other words, the world may gradually become less dependent on the dollar without becoming dependent on anything else.
That is a very different conclusion than many headlines would have us believe. So, what should long-term investors do with this information?
Probably very little. If anything, this is simply another reminder that successful investing is built on discipline, diversification, and patience - not reacting to every alarming headline.
If history is any guide, meaningful changes in reserve currency status unfold over decades, not quarters. That argues for maintaining the same disciplined investment approach that has served our clients well for decades: own a diversified portfolio, invest in high-quality businesses, maintain global exposure where appropriate, and resist the temptation to make emotional decisions based on dramatic headlines or short-term geopolitical events.
Muddy Waters sang that he had his mojo working, but it simply wasn't working on the one person he hoped to influence.
Today's U.S. dollar finds itself in a surprisingly similar position. Its influence remains extraordinary, and it continues to sit at the center of the global financial system. Yet many countries would clearly prefer a world in which they were less dependent upon it.
The irony is that wanting a different financial system and creating a better one are two very different things.
For now, the dollar's mojo is still working. It's just not working on everyone.
And understanding the difference between diversification and replacement is one more way we can continue Moving Life Forward.
©2026 Jesse Hurst
Senior Wealth Manager
Related Content
The views stated are not necessarily the opinion of Cetera and should not be construed directly or indirectly as an offer to buy or sell any securities mentioned herein. Due to volatility within the markets mentioned, opinions are subject to change without notice. Information is based on sources believed to be reliable; however, their accuracy or completeness cannot be guaranteed. Past performance does not guarantee future results.
Investors cannot directly invest in indices.
A diversified portfolio does not assure a profit or protect against loss in a declining market.
Please note Cetera Advisors LLC is not registered to offer direct investments in commodities or futures. Instead, access to this asset class is provided via mutual funds, exchange-traded funds (ETFs), and the stocks of associated companies. Investments in commodities may be affected by overall market movements, changes in interest rates, and other factors such as weather, disease, embargoes, and international economic and political developments. Commodities are volatile investments and should form only a small part of a diversified portfolio. An investment in commodities may not be suitable for all investors.
Featured Blog Image Source: iStock.com/klyaksun